Quick answer: “Disfinancified” money advice is financial guidance translated into plain, everyday language: no unexplained jargon, no 50-category budgets, no formulas presented without meaning. The core rules are simple — save a fixed share of what you earn, spend on purpose, track your money in a way you will actually keep doing, and learn the few concepts that genuinely change decisions. This guide translates the jargon, shows how to test whether simplified advice is still correct, and builds a money system you can run without a finance degree.
What Does “Disfinancified” Mean?
Break the word apart and it explains itself: “dis” (removal) plus a form of “finance” — the removal of the barriers that make money advice hard to use. Blogs writing about this idea define it the same way: taking concepts like asset allocation, amortisation, and diversification and expressing them in words a non-expert can act on, without losing the meaning.
The need is real. Financial writing is full of terms that are precise to professionals and opaque to everyone else. A reader who meets “maximise your tax-advantaged retirement vehicles” has to decode three pieces of jargon before reaching the actual instruction, which is simply: put money in accounts where you pay less tax while saving for later life. Disfinancified advice does that decoding up front. It also respects a second truth: people do not fail with money because they lack a 50-category spreadsheet. They fail because the system they were given was too complicated to maintain on a tired Tuesday evening.
Three principles run through the blogs on this keyword: clarity (simple words, explained terms), relevance (advice tied to real situations, not textbook examples), and accessibility (small steps that build on each other). Everything below follows those three.
The Jargon Translator: 20 Terms in Plain English
Keep this table. When a finance article, adviser, or app throws a term at you, look it up here first — and if a term is not here, demand the same kind of translation before acting.
| Jargon | Plain English | Why it matters to you |
|---|---|---|
| Asset allocation | How you split money between types of investment | Decides how bumpy your ride is |
| Diversification | Not putting everything in one place | One failure cannot wreck you |
| Compound interest | Interest earned on interest already earned | Why starting early beats starting big |
| Debt-to-income ratio | How much you owe compared with what you earn | Lenders use it to judge you |
| Amortisation | Paying a loan off in regular slices of interest plus principal | Explains why early payments feel mostly interest |
| Liquidity | How fast you can turn something into spendable cash | Emergency money must be liquid |
| Net worth | Everything you own minus everything you owe | The one number that summarises your position |
| Risk tolerance | How much ups and downs you can stomach without panicking | Sets how bold your investments should be |
| Index fund | A fund that buys a whole market slice instead of picking winners | Usually cheaper and steadier |
| Expense ratio | The yearly fee a fund takes, as a percentage | Small percentages compound into big gaps |
| Capital gains | Profit from selling something for more than you paid | Often taxed differently from wages |
| Emergency fund | Cash set aside for surprises, not goals | Stops surprises becoming debt |
| Credit utilisation | How much of your available credit you are using | High use can hurt your credit score |
| Inflation | Prices rising so money buys less over time | Why cash under a mattress loses value |
| Principal | The original amount borrowed or invested | Interest is charged on this |
| Equity | What you truly own in something after debts | Your share of a home, business, or company |
| Liability | Something you owe | The other side of net worth |
| Portfolio | Everything you have invested, taken together | Judge the whole, not one holding |
| Rebalancing | Adjusting back to your planned split after markets move | Keeps risk where you intended it |
| Fiduciary | Someone legally required to act in your interest | Ask any adviser whether they are one |
The 4 Rules That Carry Most of the Weight
Strip away the noise and the blogs on this topic agree on four rules. They are not glamorous, and they do not require a spreadsheet with 53 categories — a point one guide makes by contrasting viral budget templates with real life.
Rule 1: Save a fixed share first
Save 10–20% of whatever you earn or receive, and move it on payday before spending starts. The percentage matters less than the automation: money that never sits in your spending account never gets “accidentally” spent. If 20% is impossible right now, start at 5% and raise it by one point each time your income rises.
Rule 2: Spend on purpose, not on autopilot
Mindful spending is not about guilt; it is about noticing. For one month, write down every purchase in a notes app — no categories, no judgement, just the list. Most people find two or three recurring costs they barely value: subscriptions nobody uses, delivery fees that exceed the food, impulse buys that duplicate something already owned. Cancelling those is painless saving.
Rule 3: Track money in the simplest way you will sustain
The best tracking method is the one you still use in month six. For most people that is one of these: a weekly 10-minute check of bank transactions, a notes-app list, or an app that categorises automatically. If a method takes more than 15 minutes a week, it will die — and a dead system is worse than a simple one, because it also carries guilt.
Rule 4: Plan ahead for the predictable surprises
Car repairs, medical bills, school costs, and annual fees are not emergencies; they are certainties with unknown dates. Setting aside a small monthly amount for each predictable category turns crises into errands. This is the same idea as the emergency fund, applied one level down.
How to Tell Good Simple Advice from Oversimplified Advice
Simplification has a failure mode: advice can become so simple that it stops being true. “Just save more” is simple and useless to someone already stretched. “Never use credit” is simple and wrong for someone building a credit record. Use these tests before trusting any plain-language tip:
| Test | Good simple advice | Oversimplified advice |
|---|---|---|
| Does it name the exception? | “Save 10–20% — start lower if income is tight” | “Everyone must save 20%, no excuses” |
| Does it explain why? | “Fees compound, so low fees matter” | “Trust me, this fund is best” |
| Can you check it? | “Run the numbers on a free calculator” | “Studies show” with no study named |
| Does it admit limits? | “This covers basics; tax questions need a professional” | “This is all you will ever need” |
| Does it sell something? | No product attached to the advice | The “simple” answer is a paid course or app |
That third row deserves emphasis. The blogs on this keyword repeat eye-catching statistics — for example, that large majorities of people find financial terms confusing, or that simplified information speeds up decisions by a fixed percentage. Those numbers circulate without a source you can verify, and some of them contradict each other. Treat unsourced statistics in money content as decoration, not evidence. The advice itself should stand on its own logic: if the reasoning is clear and you can check the arithmetic, the statistic is unnecessary; if the reasoning is missing, no statistic rescues it.
A Disfinancified Money System, Step by Step
Here is the whole system on one page. Set it up in a weekend, then let it run.
- Open the right accounts. One spending account, one savings account, and — if you have variable income — one “holding” account where income lands before you pay yourself a steady amount.
- Automate payday. On payday, fixed amounts move automatically: savings first, then bills, then a guilt-free spending amount. What remains in the spending account is safe to spend.
- Build the cushion in order. First, a starter cushion of one month of essentials. Then, pay down high-interest debt. Then, grow the cushion to three to six months. Investing comes after the cushion, not instead of it.
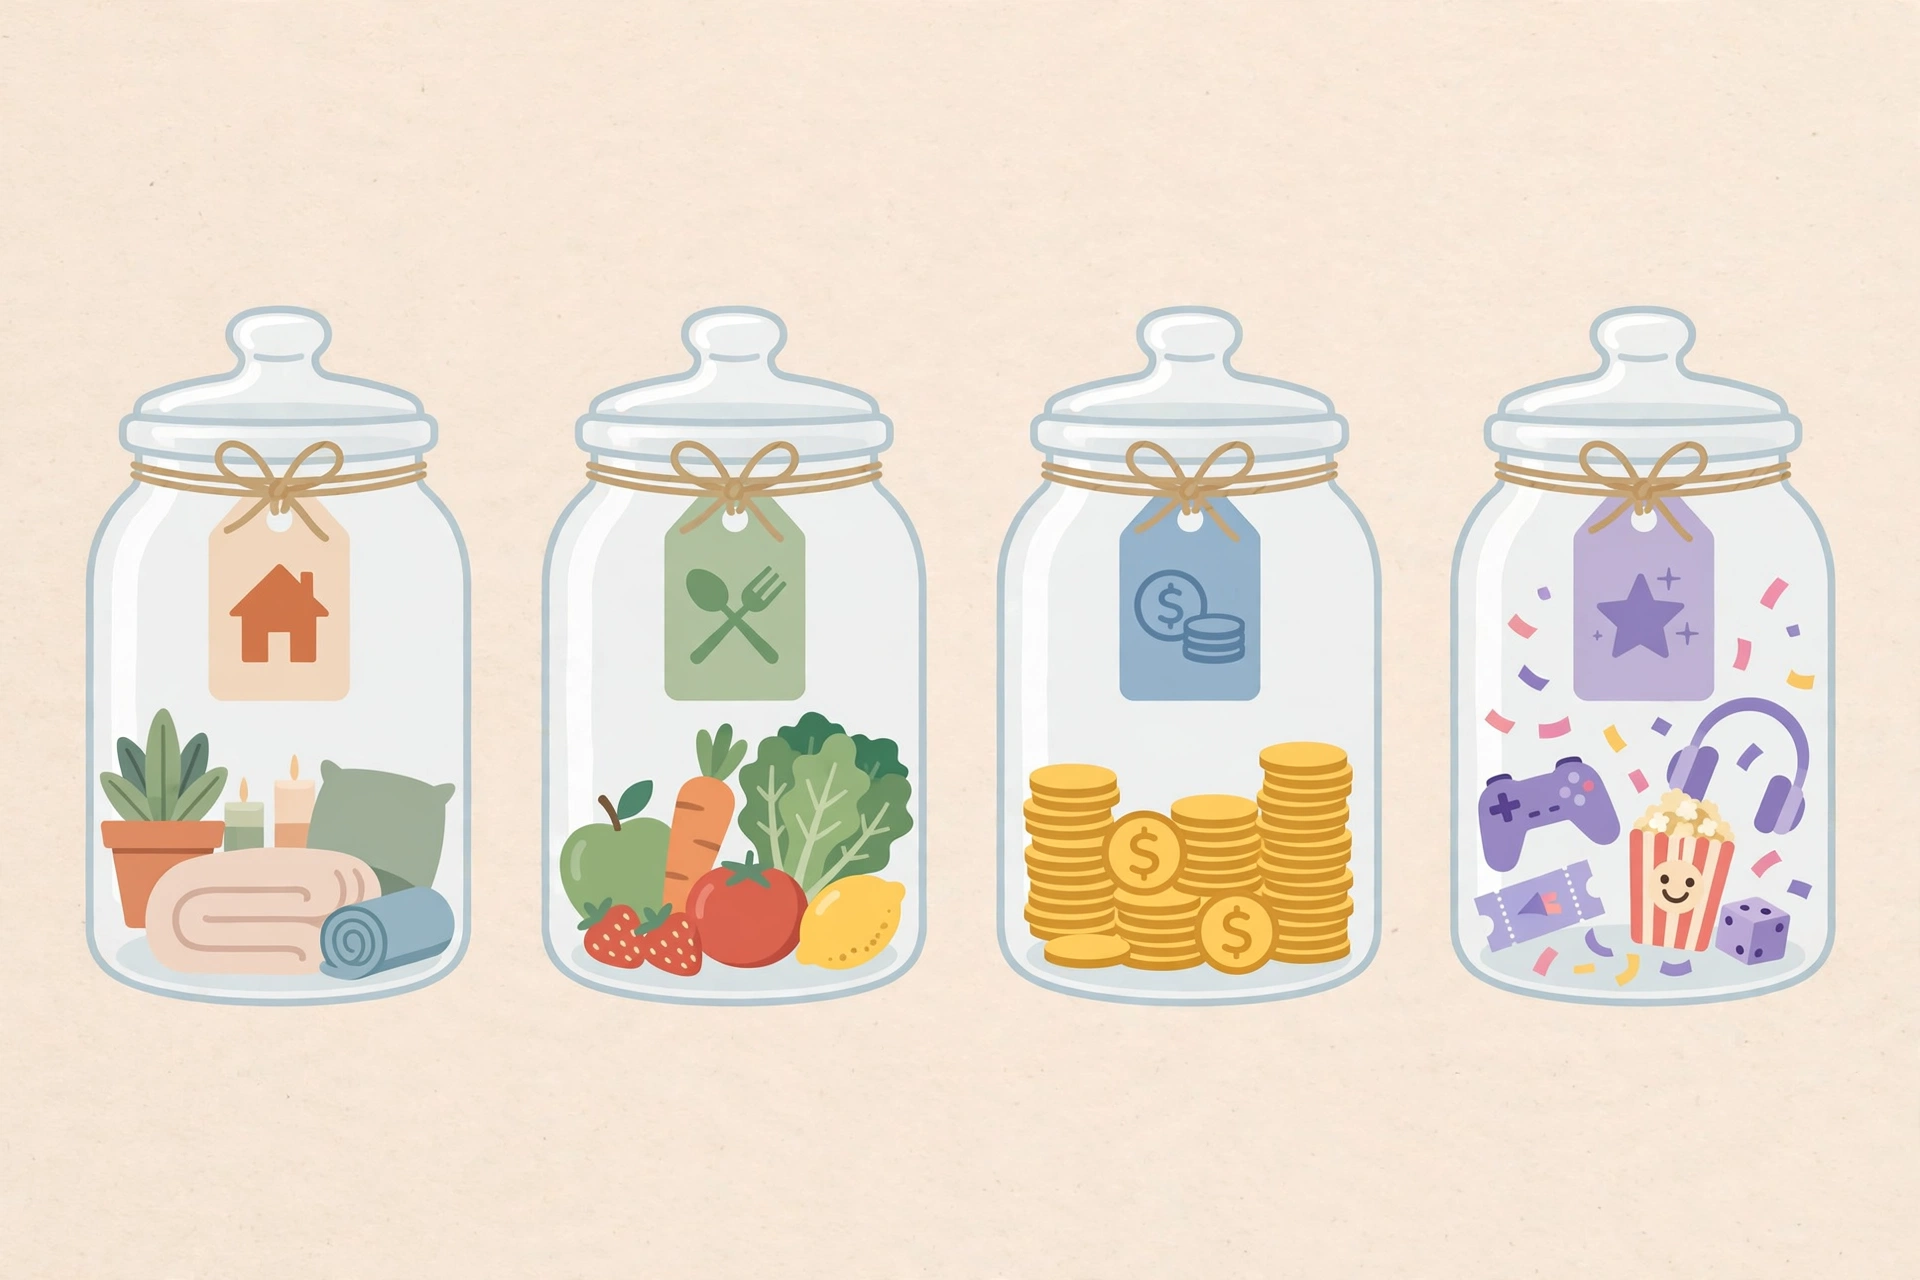
- Give every pound a job — loosely. Use broad buckets, not micro-categories: home, food, transport, savings, fun. If a bucket keeps overflowing, the budget is wrong, not you — adjust the bucket.
- Review monthly, briefly. Once a month, spend 20 minutes asking three questions: did savings move, did any bucket overflow twice, and is there one subscription or habit to cut? That is the whole review.
- Learn one concept a month. Pick one term from the translator table and learn it properly — what it means, how it affects you, and where it appears in your own accounts. Twelve terms a year turns a beginner into someone no salesperson can bluff.
| Stage | Goal | Sign it is done |
|---|---|---|
| Starter cushion | One month of essentials saved | An unexpected bill no longer becomes debt |
| Debt attack | High-interest debt cleared | No balance charged above 15–20% interest |
| Full cushion | Three to six months of essentials | You could lose income and stay calm for months |
| Investing core | Low-cost diversified investing, automated | Contributions happen without monthly decisions |
| Annual tune-up | One yearly check of insurance, tax, and goals | Coverage and goals match your current life |
When Plain Advice Is Not Enough
Honest simplification knows its boundary. Get qualified professional help — and check that the adviser’s pay does not depend on what you buy — when you face any of these: a tax bill you do not understand, cross-border income, a business with employees, a large inheritance, divorce or bereavement finances, or retirement planning with a fixed deadline. The disfinancified skill in those moments is not doing it yourself; it is being able to understand the professional’s explanation well enough to ask good questions. That is exactly what the translator table is for. For the investing side of the same idea — advice without the sales pitch — see our guide to discommercified investing, and for stripping hype out of business advice, our guide to disbusinessfied thinking.
A Month in a Disfinancified Life
Abstract rules are easier to keep when you can picture them. Here is an illustrative month — not a real person’s diary, but a realistic picture of the system in this guide running on autopilot.
Payday. Salary lands in the holding account. Automatic transfers move the savings share to the savings account, the bills amount to the bills account, and the rest to spending. No decision is made; the decisions were made once, when the system was set up.
Week one. The weekly check takes ten minutes: open the bank app, glance at transactions, note anything surprising. A subscription renewed that nobody uses — cancelled in two taps. A grocery bill higher than usual — noted, not agonised over; one week does not break a budget.
Week two. A car repair appears. It is paid from the “predictable surprises” bucket, not from a credit card, because car repairs were always a matter of when, not if. The emergency fund is untouched.
Week three. A friend recommends an investment product with an impressive name and a complicated structure. The response takes thirty seconds: “Can I explain it in two sentences?” No. So it is declined without guilt and without further research. Complexity that cannot be explained is not an opportunity; it is a warning.
Week four. The monthly review takes twenty minutes: savings moved, one bucket overflowed once (transport, because of extra trips — the bucket is adjusted, not the person blamed), and one concept from the translator table is learned properly: this month, expense ratio. The system continues, slightly better than last month.
Nothing in that month required willpower, expertise, or a finance degree. That is the point of a disfinancified system: it replaces heroic monthly effort with boring automation, and boring automation is what survives real life.
Common Traps, Translated Into Plain Language
Some traps survive precisely because they are described in language that hides what they are. Here they are, translated:
| What it is called | What it actually means | The plain-language question to ask |
|---|---|---|
| “Buy now, pay later” | A loan, split into pieces, often with late fees | “Would I still buy this if I had to pay in full today?” |
| “Zero-interest credit” | Interest deferred, not removed — miss a term and it arrives retroactively | “What happens if I am one day late?” |
| “Exclusive investment opportunity” | A product that could not attract buyers openly | “Why is this not available to everyone?” |
| “Guaranteed returns” | Either a scam or a return so low it barely beats inflation | “Guaranteed by whom, and with what assets backing it?” |
| “Premium money membership” | Paying monthly for advice you could get free | “What does this tell me that a library book does not?” |
| “Lifestyle inflation package” | Spending rises exactly as fast as income, forever | “What did I save from my last raise?” |
Related Articles
- FeedBuzzard Explained: Content Site, Ad Claims, and How to Check It
- ProgramGeeks Explained: Learning Platform, Social Community, and Game Dev
- Disquantified Explained: Teams Beyond Metrics — and the Disqualification Myth
Frequently Asked Questions
What does “disfinancified” actually mean?
It means financial advice with the jargon and complexity removed, so that ordinary readers can understand and act on it. It is a coined word used by finance blogs, not a formal financial term.
Is simplified advice less accurate than expert advice?
Good simplification keeps the meaning and drops only the decoration. Bad simplification drops the meaning too. Use the five tests in this guide — exceptions, reasons, checkability, admitted limits, and no hidden sale — to tell them apart.
How much should I save?
The commonly repeated range is 10–20% of income, but the right number depends on your income, debts, and goals. Start with whatever you can automate consistently, then raise it gradually. Consistency beats an ambitious percentage you abandon in month two.
Do I need a budget app?
No. A notes app, a notebook, or a weekly bank-statement check all work. An app helps only if you actually open it; the method you sustain is the right method.
What is the difference between an emergency fund and savings?
An emergency fund is for surprises and should stay accessible and untouched otherwise. Savings is for goals — a holiday, a deposit, a course. Mixing them means a surprise eats the holiday, or the holiday eats the safety net.
Should children learn disfinancified money rules?
Yes, and the same rules apply in smaller form: save part of any money received, spend on purpose, and track it simply. Several guides on this keyword note that the rules are deliberately simple enough for a young teenager to follow — which is also a good test of whether an adult guide is truly simple.
When should I stop doing it myself and hire a professional?
When the stakes or the complexity exceed the basics: taxes you cannot explain, cross-border income, business finances, large windfalls, or retirement decisions with a deadline. Choose a professional whose pay does not change with your choices, and use your plain-language knowledge to question their advice.
What if my income is irregular?
Use the holding-account method: all income lands in one account, and you pay yourself the same steady amount each month from it, as if you had a salary. In good months the holding account grows; in lean months it covers the gap. Set your monthly “salary” from your average income over the past six to twelve months, not from your best month. Freelancers and seasonal workers who skip this step tend to spend the good months and borrow in the lean ones — the exact cycle a disfinancified system exists to break.
How do I actually learn one concept a month?
Pick the term, then find it in your own life. Learning “expense ratio” means opening your fund or pension statement and finding the fee line. Learning “credit utilisation” means checking your card balance against your limit. A concept tied to your own numbers sticks; a concept read in the abstract fades within a week. Keep a single notebook page per concept — the plain definition, your number, and one action it suggests — and by year’s end you own a personal finance manual written in your own words.
Is “disfinancified” the same as “discommercified”?
They are cousins. Disfinancified advice removes jargon; discommercified advice removes sales pressure. The best money guidance does both — plain language, with nobody profiting from your decision.
Conclusion
Money is not complicated because it is deep; it is complicated because it is usually explained badly, by people who profit from the confusion. Disfinancified advice reverses that: plain words, four rules, a simple system, and the habit of checking every claim. Set the system up once, let automation carry it, learn one concept a month, and get professional help for the genuinely complex parts. That is not a dumbed-down version of finance. It is finance with the obstacles removed — which is what it should have been all along.